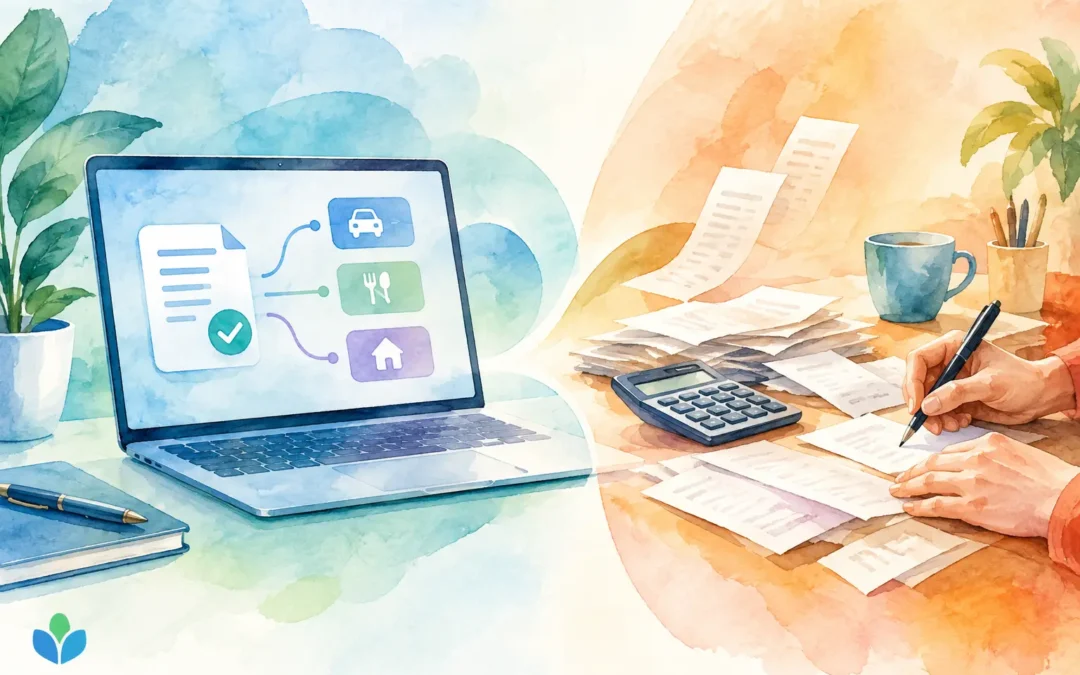
A supplier invoice arrives in three languages, priced in dollars, with a VAT charge that needs checking before month-end. In an automated expense coding vs manual process comparison, this is where the difference becomes obvious. One route means opening a spreadsheet, reading every line, choosing a category and checking the exchange rate. The other captures the invoice, suggests the treatment and sends only uncertain items for review.
For Maltese businesses, expense coding is not a minor back-office task. It affects VAT figures, management reporting, cash visibility and how quickly an accountant can close the month. The right approach is not about removing people from the process. It is about removing repetitive work from people who have better things to do.
What manual expense coding really costs
Manual coding usually begins with good intentions. A business owner or bookkeeper saves invoices in folders, enters supplier details into a spreadsheet or accounting system, assigns an expense category and records VAT. At low volume, it can appear manageable.
The problem is repetition. Ten invoices a month may take little time. Fifty invoices with mixed VAT treatment, foreign currencies and incomplete supplier information become a recurring interruption. Every document must be found, read, interpreted and entered. If an invoice is missing, someone has to chase it. If a number is mistyped, the error may not appear until the VAT return or month-end review.
Manual work also relies heavily on individual knowledge. One person may know that a particular supplier is usually software, that a hotel invoice needs a different treatment from a local service bill, or that a foreign-currency amount must be converted consistently. When that person is busy, on leave or no longer with the business, the process slows down.
This does not mean manual coding is always wrong. A very small business with only a handful of simple, predictable invoices may prefer it. It can also be appropriate for unusual, high-value transactions that need detailed judgement. But as invoice volume grows, manual coding turns bookkeeping into data entry rather than financial control.
Automated expense coding vs manual: where it changes the workflow
Automated expense coding starts at intake. Instead of asking staff to rekey data, the system extracts the supplier, invoice date, total, currency, VAT details and line information from the document itself. It then applies rules and learned supplier behaviour to propose the right expense category and tax treatment.
The practical gain is not simply faster entry. It is exception-based work. Straightforward invoices can move through the process with little or no intervention, while unusual documents are flagged for a human to check. Your team spends time making decisions, not copying totals from PDFs.
Manual coding follows the opposite model. Every invoice receives attention, whether it is a familiar monthly software subscription or a one-off purchase with unclear VAT. That approach gives a feeling of control, but it gives equal effort to simple and complex tasks. Automation applies effort where it is needed.
For example, a recurring invoice from a known Maltese supplier can be recognised and treated consistently each month. A new supplier invoice in USD with an unfamiliar VAT position can be surfaced for review. The system handles the predictable work and keeps the exception visible.
Speed matters most at month-end
Month-end pressure exposes weak processes. When invoices sit in email inboxes, WhatsApp messages and desk drawers, the final days of the month become a chase. Someone collects documents, enters data in bulk, checks categories and tries to assemble a VAT-ready picture under time pressure.
Automated intake changes the timing. Invoices can be submitted as they arrive by email, WhatsApp or dashboard upload. Data is processed continuously rather than saved for a last-minute batch. By month-end, the work is largely review rather than reconstruction.
That makes reporting more useful too. A report created weeks after the period ends is a record of what happened. A current report helps a director decide what to pay, where costs are rising and whether cash needs attention.
Accuracy improves through consistency, not blind trust
Automation is often described as more accurate than people. The more useful claim is that it can be more consistent. Manual processes produce different results when staff are rushed, tired or working from incomplete information. The same supplier can be coded differently by two people. VAT treatment can drift over time without anyone noticing.
A well-configured automated system applies the same logic to similar documents and keeps a clear record of what it processed. Supplier memory is especially valuable here. Once a supplier has been reviewed and categorised correctly, future invoices can follow that established treatment unless something changes.
However, automated coding needs sensible controls. A system cannot know commercial context that is absent from the invoice. A restaurant bill may be a legitimate staff expense, client entertainment or a non-business cost. A director or accountant still needs to make that call. Good automation makes that review faster by presenting the data clearly. It should not pretend every document is unambiguous.
VAT is where a local process earns its place
For businesses operating in Malta, VAT is not an optional extra to expense coding. The category and treatment selected for each invoice feed directly into VAT reporting. A generic workflow may capture a total correctly but still leave the user to decide how it should appear in the return.
That is where manual work creates avoidable risk. A missed VAT amount, incorrectly treated overseas invoice or inconsistent category can distort return figures and generate extra accountant review. The cost is not just the correction. It is the uncertainty around whether the period is complete.
Automation should support Malta-specific VAT categorisation and produce figures that are usable at filing time. MyAccountant, for example, processes invoices, handles foreign-currency conversion into euros and prepares monthly summaries with pre-filled Malta CFR VAT return figures. The objective is clear: fewer spreadsheet checks and a cleaner review trail.
Foreign currency deserves particular attention. Manual conversion often means searching for rates, applying them inconsistently or using a figure that cannot be easily traced later. A system that records the source document and converts values consistently creates a much stronger basis for reporting and accountant review.
The trade-off: automation still needs ownership
The strongest process is rarely fully manual or fully hands-off. It is automated processing with accountable review.
Business owners should approve expenses according to their internal controls. Bookkeepers and accountants should review exceptions, unusual VAT treatment and material transactions. Automation should capture, classify, calculate and prepare the routine information in the background.
This matters for accountancy firms too. Manually entering every client invoice does not scale well. A firm needs a consistent intake route, reliable source documents and clear exceptions across multiple entities. The accountant’s time is better used reviewing judgement calls, advising clients and checking compliance than transcribing invoice references.
Before choosing a tool or changing your workflow, test it against the documents that cause the most friction. Include foreign supplier invoices, receipts with limited information, mixed VAT scenarios and recurring invoices in different languages. The question is not whether the software can read a clean PDF. The question is whether it reduces the real work that slows your month-end down.
When manual coding may still be enough
Manual coding can remain practical when invoice volume is genuinely low, transactions are simple and one person has the time and expertise to maintain the records properly. It may also be the preferred approach during a short transition period while categories, approvals and supplier information are being cleaned up.
But do not confuse familiarity with efficiency. A spreadsheet can feel simple because everyone knows how to use one. That does not make it the best system for handling growing volumes, VAT deadlines and multiple sources of documents.
A useful threshold is not a fixed invoice number. It is the point at which coding starts being postponed, month-end becomes stressful, or your accountant spends time correcting routine entries. Once that happens, the process is already costing more than it appears.
The practical aim is simple: let software handle the invoices it understands, let people review the ones that need judgement, and keep every figure ready for the moment you need it.