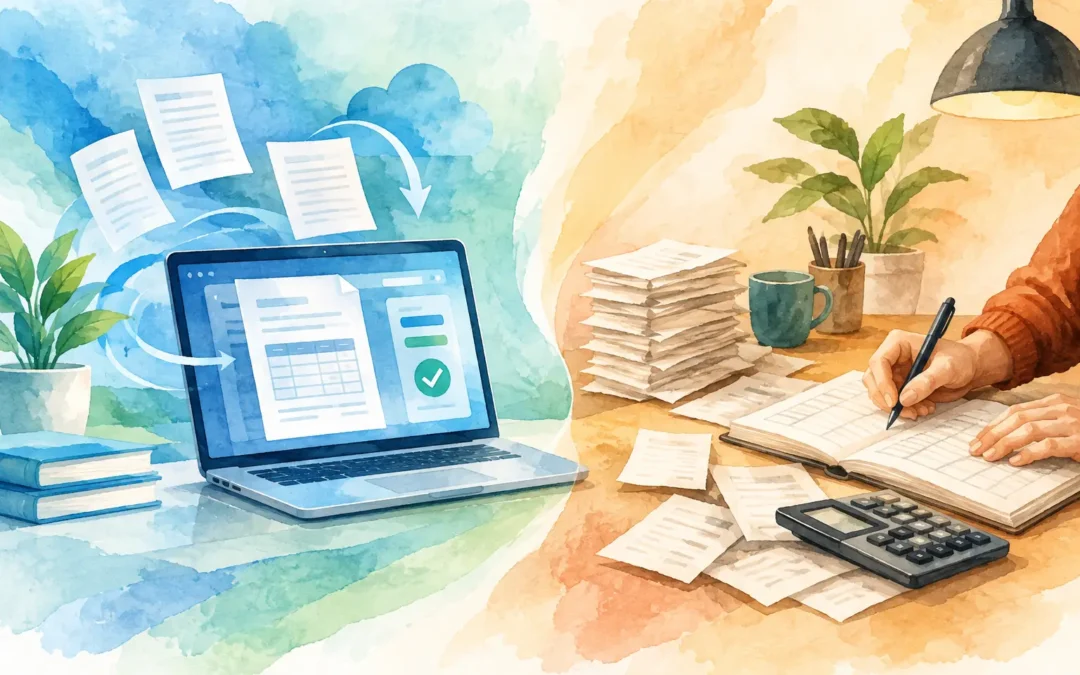
A supplier invoice arrives in a WhatsApp chat at 19:40. Another is buried in an email thread. A third is a crumpled receipt in someone’s wallet. OCR vs manual bookkeeping is not a theoretical choice for a Malta business. It determines whether these documents become useful financial data this month, or another end-of-quarter spreadsheet problem.
Manual bookkeeping can feel cheaper because it uses tools you already have: inboxes, paper folders and spreadsheets. The real cost appears in the repeated work around them. Someone has to find every document, type each amount, identify the supplier, decide the VAT treatment, convert foreign currency and check the totals again. Then an accountant may need to repeat parts of that work before filing.
OCR vs manual bookkeeping: the operational difference
Manual bookkeeping turns every invoice into a small administration task. A person reads the document, enters the details into a ledger or spreadsheet, selects a category and stores a copy. The process is familiar, but it scales in a straight line: twice as many invoices generally mean close to twice as much work.
OCR, or optical character recognition, extracts text and values from an invoice image, PDF or photograph. In a bookkeeping workflow, that means the supplier name, invoice number, date, totals, VAT figures and currency can be captured without being typed character by character. Good systems go further by matching fields to the right bookkeeping structure and learning from recurring suppliers.
That distinction matters. Basic OCR that merely turns a PDF into searchable text still leaves a person to interpret and enter the accounting data. Invoice-processing automation uses OCR as the capture layer, then applies rules, supplier history and VAT logic to make the output ready for review.
For a business processing a handful of straightforward invoices each month, manual entry may be tolerable. For a growing SME, a busy director or an accountancy practice handling multiple clients, it soon becomes a bottleneck. The question is not whether people can enter data accurately. They can. The question is whether their time is best spent doing it repeatedly.
Where manual bookkeeping still earns its place
Manual bookkeeping has one genuine advantage: a knowledgeable person can apply judgement in unusual situations immediately. A one-off legal invoice, a mixed business and private expense, or a supplier document with unclear tax wording may need context that no automated system has yet seen.
It can also be a sensible temporary approach for a new business with very low document volume and simple domestic transactions. If there are five invoices a month, no foreign currencies and no VAT registration, setting up a more structured process may not be urgent.
But manual does not automatically mean controlled. Spreadsheet cells can be overwritten, invoice numbers can be missed and documents can sit in private inboxes. A careful bookkeeper reduces those risks, but the business is still relying on consistent human effort at every stage.
The most common manual failure is not poor accounting knowledge. It is interruption. A director starts entering invoices, gets pulled into operations, promises to finish later and reaches month-end with an incomplete picture. The bank balance might be visible, but costs, reclaimable VAT and supplier liabilities are not reliably up to date.
Where OCR changes the economics
OCR earns its place when it removes repetitive capture without removing oversight. A team member should be able to forward an invoice by email, send it through WhatsApp or upload it from a dashboard. The document enters one queue, rather than waiting in several personal folders for someone to collect it.
The immediate gain is speed, but speed alone is not the point. Consistent data capture makes the entire monthly process easier to manage. Invoices are stored alongside their extracted data. Duplicate documents are easier to spot. Supplier names become standardised. Search becomes practical when an accountant asks for a particular invoice six months later.
Foreign-currency invoices show the difference clearly. With manual bookkeeping, a euro value needs to be calculated, recorded and supported by a consistent rate. This creates room for small errors that become frustrating reconciliation work later. Automated currency conversion can apply the required conversion consistently, while retaining the original currency and source document for review.
VAT is where a generic automation tool can become more work than it saves. Malta businesses may deal with standard-rated purchases, exempt transactions, EU supplier invoices, reverse-charge treatment and expenses where VAT cannot simply be assumed. OCR can identify the amounts on the page, but the bookkeeping workflow must still categorise them correctly for the relevant return.
That is why Malta-specific processing matters. MyAccountant captures multilingual supplier invoices, applies VAT categorisation and prepares monthly summaries with pre-filled Malta CFR VAT return figures. The aim is not to make VAT invisible. It is to make the routine treatment consistent and surface the documents that need professional judgement.
OCR is not a substitute for controls
There is a bad version of automation: extract a number, post it automatically and hope for the best. That approach can make errors travel faster. A poorly photographed invoice may produce a misread digit. A supplier might change its VAT treatment. A document may be a pro forma invoice rather than a final invoice.
The right model is automation for the predictable work and human review for exceptions. High-confidence, recurring invoices should not demand the same attention as an unfamiliar foreign supplier or an invoice with a tax amount that does not reconcile. This is more efficient than reviewing every field with equal intensity.
A practical OCR workflow should retain the original document, show the captured values clearly and make exceptions easy to identify. It should also maintain an audit trail of what was received, how it was classified and what was changed during review. That is useful for internal discipline as well as accountant queries.
Accountants do not lose their role in this model. Their role improves. Instead of chasing blurry attachments and rebuilding client records from spreadsheets, they can review exceptions, assess treatment and advise on the decisions that affect tax, cash flow and reporting quality.
A practical decision for Malta businesses
Choose manual bookkeeping when volume is genuinely low, transactions are simple and a competent person has protected time to keep records current. It can work well for a short period, provided documents are stored consistently and VAT obligations are understood.
Choose OCR-led bookkeeping when invoice capture is already fragmented, month-end depends on a last-minute catch-up, several people receive supplier documents, or foreign currency and VAT treatment create regular friction. These are not signs that the business has failed to stay organised. They are signs that the current process has outgrown manual entry.
Do not measure the choice only by the cost of software versus the hourly rate of a bookkeeper. Include the cost of delayed reporting, missed VAT recovery, duplicate effort, poor visibility over supplier spend and the director time spent looking for documents. A process that appears inexpensive can be costly when it prevents timely decisions.
Build a workflow around exceptions, not entries
The strongest bookkeeping process is deliberately unremarkable. Invoices arrive through channels people already use. Data is captured once. Routine VAT and currency handling follows a consistent method. The owner or accountant reviews the items that genuinely require judgement, then has current figures ready for month-end.
Start with the documents that cause the most chasing: emailed invoices, WhatsApp receipts and overseas supplier bills. If those can enter one controlled workflow without someone retyping them into a spreadsheet, the benefit becomes visible quickly.
The goal is not to remove people from finance. It is to remove them from copying information they already have. Keep human attention for the decisions that need it, and let the repetitive invoice work get done before it becomes another month-end delay.